

Please note: borrowing money costs money.
Short-term commercial property financing in the Netherlands for BV investors
Short-term commercial property finance is a temporary loan secured against an investment property, used to buy and renovate before refinancing to a long-term facility. Terms run in months rather than decades. Specialised lenders assess the project, the collateral value and your exit strategy, rather than applying standard retail lending criteria.
Bouvy Advies is an independent adviser (AFM licence 12046005). We compare these facilities, request current written quotations per lender, calculate the full cost and align the structure with your liquidity and long-term investment strategy.
When does a private lender make sense?
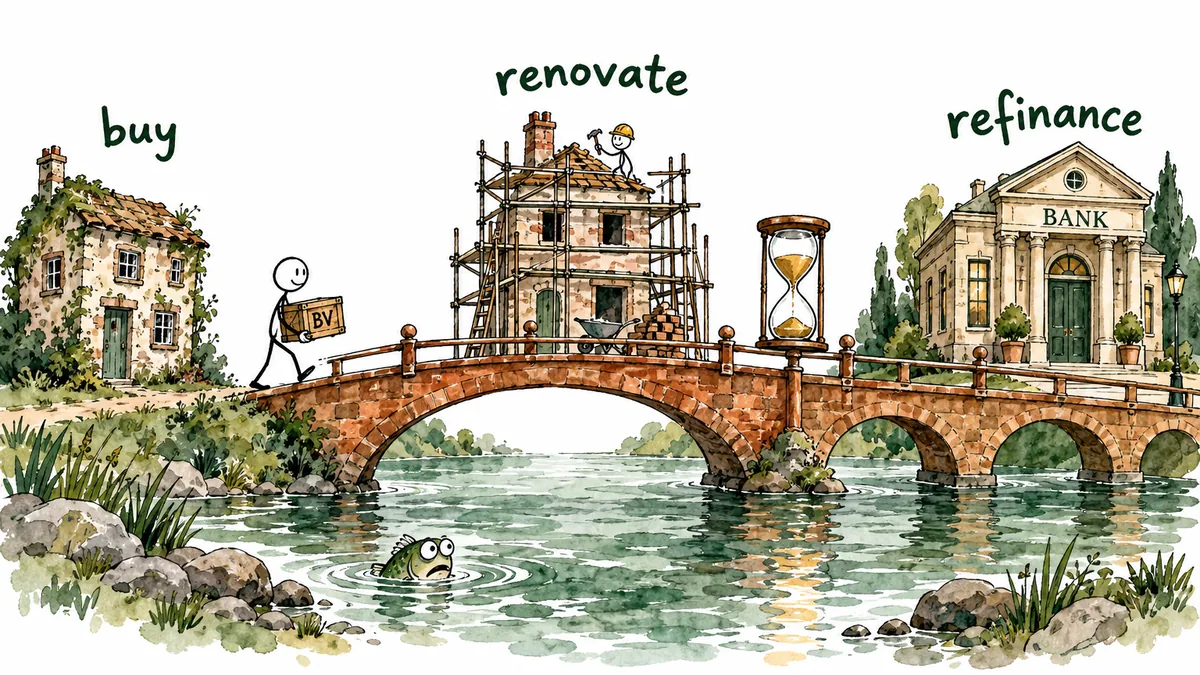
A private lender can make sense when your BV needs temporary finance to buy and renovate investment property before long-term refinancing. These loans are secured against the property and run in months rather than decades. Specialised lenders assess your project, the collateral value and your exit strategy rather than standard retail lending criteria.
- The property requires renovation, conversion or redevelopment before it becomes fully “bankable”.
- You plan to use short-term finance and refinance to a long-term bank or buy-to-let mortgage afterwards.
- You invest through a BV and need tailor-made solutions in terms of loan-to-value (LTV), construction deposit and securities.
Which lenders do we work with?
We work most frequently with DCMF and also place business with Pearl Capital and RNHB. We compare lenders for your BV based on your project, timeline and existing portfolio rather than defaulting to one provider. DCMF's bridge loan application form (February 2026) asks for the following.
- At least two years of demonstrable property investment experience.
- The application is made in the normal course of your profession or business.
- The property is not intended for occupation by you or by direct family members.
- Market value is stated both in current condition and after renovation.
- A documented exit strategy per property, plus the requested term in months.
What are the typical terms?
Terms vary by lender, with no market standard. Pearl Capital lists a maximum loan term of 18 months for residential or mixed-use property (one pager, PDF date November 2025). DCMF releases construction deposits against your approved invoices (general terms, July 2022). We omit LTV, loan size and deposit percentages because one lender's documents conflict.
We deliberately publish no loan-to-value, maximum loan size or construction deposit percentage on this page, and the reason is worth knowing: we hold two documents from the same lender that do not line up on exactly those three figures, and neither carries a version date of its own. Publishing either set would give you a number that looks precise and is not.
These terms come from the lenders' own documents:
- Pearl Capital lists a maximum loan term of 18 months in its criteria (one pager, PDF date November 2025) and its brochure (PDF date February 2026). The criteria cover residential or mixed-use property only.
- According to DCMF's general terms (July 2022), the construction deposit is paid out at your request against contractor and supplier invoices you have approved, following the procedure in the loan agreement. DCMF may withhold payment if an invoice does not meet that procedure.
Neither Pearl Capital document states a version date, so treat the PDF dates as approximate. The two Pearl Capital documents disagree on loan-to-value and maximum loan size, and state the construction deposit maximum without a common basis: one gives it as a share of the total loan, while the other gives no basis. That is why you will not find those three figures here. For your project we request a current written quotation per lender, dated and confirmed in writing, and compare those side by side.
We deliberately do not publish indicative interest rates or arrangement fees on this page. Pricing in this segment moves, it is quoted per project and per risk profile, and a stale figure on a website is worse than no figure at all. We request a current written quotation per lender for your specific project and translate the offers into comparable scenarios before you commit.
What are the risks of a bridge loan in commercial property financing in the Netherlands?
A key risk of a commercial property bridge loan is that your sale or refinancing comes late or fails. Pearl Capital covers only residential or mixed-use property, for up to 18 months (one pager, PDF date November 2025). DCMF requests a documented exit strategy per property in its bridge loan application form (February 2026).
- A late exit: according to DCMF's general terms (July 2022), extension costs apply if the full amount due has not been received by the end date, unless agreed otherwise in writing. These costs are due at every extension, and DCMF increases exit costs for every further extension beyond 18 months.
- Interest on the deposit: according to DCMF's general terms (July 2022), interest is calculated on the outstanding principal and the construction deposit. You therefore also pay interest on money still in the deposit.
- Early repayment costs: according to DCMF's general terms (July 2022), exit costs are due when the loan ends before the end date or is repaid early in full, and early repayment requires at least 30 days' written notice. DCMF increases exit costs if the actual term is less than half the legal term, and you pay at least three months' interest if the loan ran less than three months.
- Refinancing has its own tests: according to RNHB's financing guide (January 2026), long-term investment financing tests rent against interest and, depending on property type and repayment form, against interest and repayment. That guide also requires a valuation report no older than six months on the application date.
We request a current written quotation per lender and calculate the total cost over your expected term. We also calculate a scenario in which your exit comes later than planned.
Who advises BV investors on short-term property finance in the Netherlands?
Bouvy Advies is an independent adviser in Naarden (Het Gooi), serving BV investors across the Netherlands under AFM licence 12046005. We compare DCMF, Pearl Capital and RNHB for short-term property finance with construction deposits. We request current written quotations from each lender and calculate total costs, including a later exit scenario. We advise on finance, not tax.
We support you by:
- Assessing your project (purchase, renovation, value now and after works, rental potential).
- Comparing lender terms (interest, fees, LTV, construction deposit rules, term).
- Calculating total cost, liquidity impact and refinancing scenarios.
- Coordinating with valuers, notaries and, where relevant, your accountant or tax adviser.
This gives you a realistic, numbers-based view of both the opportunities and the risks, before you tie up capital in a project. Note that we advise on the financing. We are not tax advisers, so the tax treatment within your BV is something we coordinate with your accountant.
Frequently asked questions
What is short-term commercial property finance? +
Can I arrange this through a Dutch BV? +
Do you also help companies get a bank loan to buy a property for their own business, such as a warehouse? +
What does a lender require from me? +
Our BV has just been incorporated, so there are no annual accounts yet. Is that a problem? +
Do I need to be present at the valuation to explain the planned renovations? +
What is an exit strategy and why does it matter? +
Is bridge financing risky? +
Is there a cheaper alternative to a bridging loan? +
How does a construction deposit (bouwdepot) work? +
What will it cost me? +
Schedule an initial consultation
Are you planning to purchase and renovate an investment property through your BV and looking for short-term commercial property finance with a construction deposit? Get in touch with Bouvy Advies for an initial, no-obligation assessment and a comparison of specialised private lenders in the Dutch market.
Planning your next property project?
In a free, no-obligation call we go through your project, compare the specialised private lenders and calculate the full cost before you commit.